
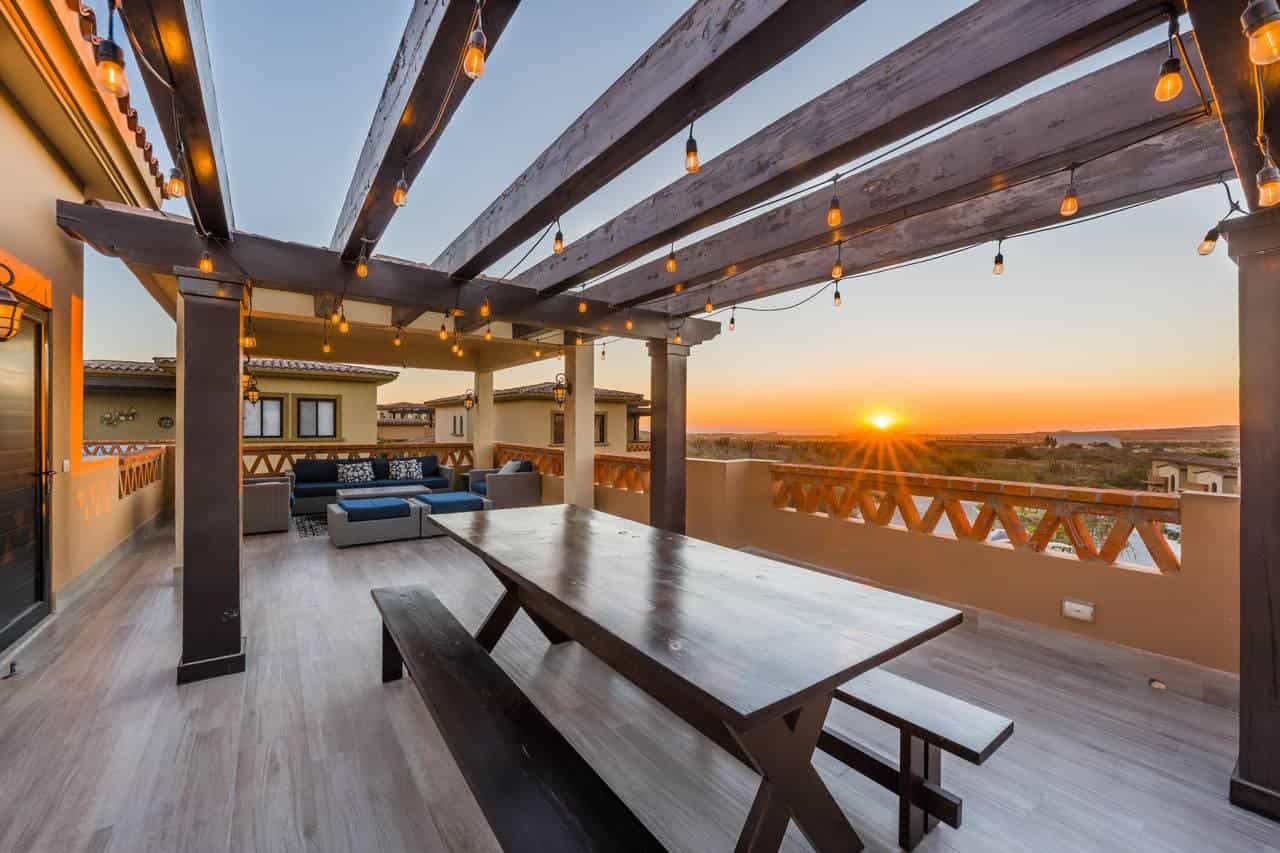
Nestled along the dramatic Pacific coastline of the Baja Peninsula, Diamante Los Cabos represents the pinnacle of luxury resort living. Renowned for its world-class golf courses designed by Davis Love III and Tiger Woods, private crystal lagoons, and immaculate luxury estates, Diamante attracts high-net-worth buyers from around the globe. For buyers originating from the United States and Canada, securing a piece of this paradise is a compelling lifestyle investment. However, navigating the legal framework and options for financing a home in diamante los cabos requires clear guidance tailored specifically to cross-border buyers.
Contrary to common misconceptions, non-Mexican citizens can seamlessly own real estate in prime coastal regions. Whether you are seeking a full-time residence, a multi-generational vacation villa, or an income-generating rental property, understanding how cross-border loans, developer terms, and equity strategies work will ensure a smooth acquisition. This practical guide covers everything US and Canadian buyers need to know about financing luxury real estate in Diamante.
Understanding Foreign Ownership: The Mexican Bank Trust (Fideicomiso)
Before diving into loan structures, it is essential to understand how foreign ownership works legally in Cabo. Under Article 27 of the Mexican Constitution, property located within 50 kilometers (31 miles) of the coastline or 100 kilometers of an international border falls into what is historically termed the “Restricted Zone.” Because Diamante is situated directly on the Pacific shore, foreign buyers acquire property through a bank trust known as a Fideicomiso.
The Fideicomiso is established through a Mexican bank, which acts as the trustee. However, as the buyer, you are named the sole beneficiary of the trust. You hold full ownership rights, meaning you can sell, rent, remodel, expand, or pass the property down to designated heirs. The trust is granted for an initial term of 50 years and is endlessly renewable for nominal administrative fees.
To establish a Fideicomiso, authorization must be granted by the Mexican Ministry of Foreign Affairs (SRE). Major institutional lenders providing cross-border financing are fully accustomed to working within the Fideicomiso legal framework, securing their mortgage against your beneficial rights to the property.
Key Options for Financing a Home in Diamante Los Cabos
While cash transactions historically dominated Mexican resort markets, the financing ecosystem for international buyers has evolved significantly. Today, US and Canadian purchasers can choose from several viable options when exploring buy Diamante real estate opportunities.
1. Developer Financing
One of the most streamlined methods for financing a property within master-planned communities is directly through the developer. Diamante and its internal neighborhood developments periodically offer direct developer financing programs for select single-family homes, luxury villas, or pre-construction estate sites. Key characteristics of developer financing include:
- Simplified Approval: Minimal underwriting requirements compared to traditional banks, often focusing primarily on credit history and proof of down payment.
- Flexible Terms: Typically offering 3- to 10-year term lengths with balloon payments or fixed amortizations.
- Down Payment Requirements: Generally ranges between 30% and 50% of the purchase price.
- Competitive Interest Rates: Often set as fixed USD rates slightly above conventional US mortgage rates.
2. Cross-Border Mortgages (USD Lenders)
Specialized institutional lenders in North America offer mortgages specifically structured for US and Canadian citizens purchasing residential property in Mexico. These loans are denominated in US Dollars (USD), eliminating foreign exchange risks for North American buyers.
Working with a cross-border lender allows you to keep your liquidity intact while leveraging your existing assets. Key details of cross-border loans include:
- Loan-to-Value (LTV): Typically up to 60% to 70% of the property’s appraised value.
- Loan Terms: Fixed-rate options ranging from 15 to 30 years.
- Underwriting Criteria: Similar to domestic loans in North America, requiring tax returns, debt-to-income (DTI) verification, W-2s/NOAs, asset statements, and standard credit reports.
3. Home Equity Lines of Credit (HELOC) or Asset-Backed Loans in North America
Many affluent buyers choose to finance their resort home by leveraging primary residences or investment portfolios back home. Utilizing a Home Equity Line of Credit (HELOC) or a securities-backed line of credit in the US or Canada often yields lower interest rates than foreign property loans.
By securing funds domestically, buyers effectively complete the transaction in Mexico as cash buyers. This simplifies the escrow process in Los Cabos, shortens closing timelines, and avoids additional Mexican mortgage setup fees.
4. Mexican Bank Mortgages
Major Mexican financial institutions (such as Scotiabank, BBVA, and Santander) do offer mortgages to foreign nationals. However, these loans are usually denominated in Mexican Pesos (MXN). While attractive if you earn income in Pesos, currency fluctuations can make debt servicing unpredictable for buyers holding assets primarily in USD or CAD. Furthermore, bureaucratic processing times for local bank loans tend to be longer.
Evaluating Property Types and Price Points in Diamante
Your choice of financing may vary depending on the exact neighborhood and style of real estate you select within the resort complex. Understanding how much luxury homes cost in Diamante helps determine required down payments and lending requirements.
Properties within Diamante master-planned communities span a wide spectrum of luxury product types:
- Custom Estate Lots: Land purchases in private enclaves like Sunset Hill or Beach Estates often feature specialized lot-purchase loans or developer land terms.
- Golf Villas and Residences: Turnkey properties along the El Cardonal or Dunes courses often qualify for standard cross-border mortgage programs due to completed titles and clear appraisal standards.
- Pre-Construction Homes: Staged developer financing is popular for pre-construction, where buyers make progressive payments corresponding to construction milestones.
Similar luxury resort communities across Baja, such as nearby luxury developments like Quivira Los Cabos or hilltop private enclaves like Pedregal real estate, share similar cross-border lending parameters, though internal developer terms remain distinct to each community.
The Purchasing and Financing Process: Step-by-Step
Understanding the roadmap for financing a home in Diamante Los Cabos empowers buyers to navigate the luxury transaction smoothly. Here is what to expect during the typical acquisition process:
Step 1: Financial Pre-Approval
Before submitting an offer on a home in Diamante, secure pre-approval from a cross-border mortgage lender or arrange your domestic financing strategy. Knowing your liquid capital position and maximum loan commitment clarifies your search criteria.
Step 2: Offer and Earnest Money Deposit
Once you select your property, a formal Purchase and Sale Agreement (PSA) is drafted. Upon seller acceptance, an earnest money deposit (typically 5% to 10% of the purchase price) is transferred into a secure, neutral US-based escrow account.
Step 3: Title Search and Due Diligence
Your chosen attorney and lender conduct an exhaustive search on the property title to verify that the estate is free of liens, encumbrances, or municipal tax disputes. Professional appraisals and physical home inspections are executed concurrently.
Step 4: Fideicomiso Creation & Lender Registration
The closing attorney coordinates with the designated Mexican trustee bank to establish your Fideicomiso. If utilizing a mortgage, the lender’s legal team collaborates with the bank and local Notary Public (Notario Público) to register the mortgage lien within the trust deed.
Step 5: Closing at the Public Notary
In Mexico, a Notary Public is a state-appointed attorney with heavy legal responsibility. The Notary oversees tax payments, title transfer legality, and deed registration in the Public Registry. Once all signatures are complete and full loan funds are disbursed from escrow, ownership rights transfer to you.
To review the full trajectory of acquiring property in the area, read our detailed guide on the Diamante home buying journey.
Budgeting for Closing Costs and Additional Expenses
When structuring your loan amount, remember to factor transaction costs into your total capital deployment. In Mexico, buyer closing costs are separate from standard real estate broker commissions (which are paid by the seller).
Expect closing expenses to average between 4% and 6% of the property’s purchase price. Key components include:
- Acquisition Tax (ISAI): A municipal real estate transfer tax (typically 2% to 3.5% depending on property value and location).
- Notary Fees: Official fees set by law for deed notarization and legal processing.
- Fideicomiso Setup Fees: Initial bank establishment charge (approx. $1,000 to $2,000 USD) plus the first year’s annual maintenance fee (approx. $500 to $700 USD).
- SRE Permit: Government authorization fee for foreign foreign beneficiary status.
- Title Insurance: While optional, obtaining title insurance through major US providers (such as Stewart Title or First American Title) offers added peace of mind for cross-border buyers.
- Lender Origination & Appraisal Fees: Standard underwriting and valuation charges associated with your loan approval.
Tax and Legal Implications for US & Canadian Citizens
Acquiring real estate internationally involves cross-border tax considerations. It is strongly recommended to consult a qualified CPA or cross-border tax specialist who understands both Mexican tax laws and home country regulations.
- For US Citizens: The US IRS taxes worldwide income. Holding a foreign bank trust (Fideicomiso) generally requires annual reporting (such as IRS Forms 3520 / 3520-A), though modern foreign trust rules often streamline residential properties. Mortgage interest deductions may apply depending on your tax structure and primary/secondary residence status. For official tax reporting requirements, consult the Internal Revenue Service.
- For Canadian Citizens: Canada treats foreign real estate ownership differently based on residency status and property usage. If renting the home out when not in personal use, tax treaties between Canada and Mexico prevent double taxation through foreign tax credits.
Frequently Asked Questions (FAQ)
Can US and Canadian citizens get a mortgage in Mexico easily?
Yes. Specialized cross-border lenders cater specifically to North American buyers, utilizing US-style underwriting standards. While approval requires documentation like tax returns and bank statements, the process is structured specifically for non-Mexican buyers.
Are interest rates higher for foreign property financing in Cabo?
Cross-border mortgages in Mexico typically carry interest rates 1.5% to 3% higher than primary domestic US or Canadian mortgage rates, reflecting international legal handling and specialized asset management. However, using a HELOC back home can help secure lower interest rates.
Do I need to speak Spanish or be physically present to complete closing?
No. Real estate contracts, loan agreements, and legal documents are presented with English translations. Furthermore, if you cannot attend closing in person, you can grant a limited Power of Attorney (POA) to your legal representative to sign the final deeds at the Notary Public office.
Can rental income from my Diamante home help pay off my loan?
Yes, properties within Diamante enjoy high demand for luxury vacation rentals due to top-tier amenities, golf courses, and beach clubs. Many homeowners utilize rental income to offset property maintenance, HOA dues, and mortgage obligations. Explore active Diamante homes for sale to review current property configurations and rental potential.
Conclusion
Financing a home in Diamante Los Cabos is a viable, well-established avenue for foreign buyers seeking entry into one of Mexico’s most prestigious master-planned communities. By exploring your options—whether through custom developer arrangements, cross-border USD loans, or home equity structures—you can comfortably secure a world-class luxury residence tailored to your long-term wealth strategy.
Working alongside experienced real estate advisors and legal experts familiar with cross-border luxury transactions makes the purchase process seamless. Explore our latest property listings, learn about private neighborhood enclaves, and contact our team today at Diamante Properties to begin your journey toward owning a coastal estate in Cabo.


